Buying a Car With Negative Equity: Trade-In Options, Costs, and What to Do
Owing more on your car loan than your vehicle is worth can make buying another car expensive. Learn how to calculate negative equity, compare trading in, selling privately, paying the shortfall, or keeping your current car, and understand the costs and risks of rolling unpaid debt into a new auto loan.
In this article
- What Does Negative Equity Mean When Buying Another Car?
- How to Calculate Negative Equity on Your Current Car
- Step 1: Get your current loan payoff amount
- Step 2: Estimate your vehicle's current value
- Step 3: Subtract the vehicle value from the payoff amount
- Why You May Owe More Than Your Car Is Worth
- Your vehicle depreciated faster than you paid down the loan
- You made a small down payment
- You chose a longer loan term
- You rolled previous debt into your current loan
- Your vehicle's condition or mileage reduced its value
- Can You Trade In a Car With Negative Equity?
- What Happens When You Roll Negative Equity Into a New Car Loan?
- Your new loan balance becomes larger
- You may pay more interest
- Your monthly payment may increase
- You may become upside down again
- Your Options When You Have Negative Equity
- Option 1: Keep your current car and wait
- Option 2: Pay the negative equity in cash
- Option 3: Sell the vehicle privately
- Option 4: Trade in the vehicle and roll over the negative equity
- Option 5: Refinance your current car loan
- Is It Better to Sell Privately or Trade In Your Car?
- What Does Negative Equity Actually Cost? A Worked Example
- Option A: Pay the $4,000 shortfall in cash
- Option B: Roll the $4,000 into the new loan
- Option C: Keep the current vehicle and delay buying
- Comparing the three choices
- How to Avoid Negative Equity on Your Next Car
- Make a larger down payment when practical
- Choose a vehicle you can afford comfortably
- Compare loan terms carefully
- Avoid rolling negative equity into future purchases
- Compare the actual vehicle price and financing separately
- What to Check Before Signing a New Car Financing Contract
- How to Confirm Your Previous Car Loan Was Paid Off
- Should You Buy Another Car Now or Wait?
- Conclusion
If you owe more on your car loan than your vehicle is worth, replacing your car can become more expensive than expected. The difference between your loan payoff and the vehicle's current value is called negative equity. It is also commonly described as being upside down on a car loan.
You can usually trade in a vehicle with negative equity, but the remaining debt does not automatically disappear. Depending on the transaction, you may need to pay the difference yourself, include it in your next auto loan, or consider alternatives such as selling privately or keeping your current car.
The least expensive choice depends on how much you owe, what your vehicle is worth, how much longer you can keep driving it, and the financing terms available for your next purchase.
Before visiting a dealership, calculate your actual shortfall and compare the total cost of each option. A lower monthly payment does not necessarily mean a less expensive deal.
What Does Negative Equity Mean When Buying Another Car?
Negative equity occurs when your outstanding auto loan payoff is higher than the amount you could reasonably receive for your vehicle.
For example:
-
Your current loan payoff is $20,000.
-
A dealership offers $16,000 for your vehicle.
-
The difference is $4,000.
That $4,000 is your negative equity.
Your vehicle may have lost value faster than you have paid down the loan. This can happen because of depreciation, a small down payment, a long loan term, or a combination of factors.
When you trade in the vehicle, the dealership must account for the outstanding loan. The trade-in offer does not automatically cover everything you owe.
If you purchase another vehicle, the remaining $4,000 may be:
-
Paid by you before or during the transaction.
-
Added to the financing for your replacement vehicle, if the lender approves.
-
Addressed through another arrangement agreed upon by the parties.
The important point is that negative equity is existing debt, not a discount on your next vehicle. If you finance it again, you are borrowing more money to cover an obligation from your previous purchase.
How to Calculate Negative Equity on Your Current Car
Before deciding whether to trade in your vehicle, calculate the difference between your actual loan payoff and its current market value.
Use this formula:
Negative Equity = Loan Payoff Amount − Vehicle Value
If the result is positive, you have negative equity. If the result is negative, you have positive equity.
Step 1: Get your current loan payoff amount
Contact your lender and request a payoff quote.
Do not rely only on the balance displayed on your monthly statement. The payoff amount may differ because of accrued interest, fees, or other charges.
Ask your lender for:
-
The exact payoff amount.
-
The date through which the quote is valid.
-
Any applicable payoff fees.
-
Instructions for completing the payoff.
The payoff amount is the figure you should use when calculating your shortfall.
Step 2: Estimate your vehicle's current value
Find out what your car may be worth as a trade-in.
You can use vehicle valuation resources such as:
-
Edmunds: Provides vehicle research, valuation information, and automotive market insights.
-
Kelley Blue Book: Offers vehicle valuation estimates that can help you understand potential trade-in and private-sale values.
Enter accurate information about your vehicle, including its year, make, model, mileage, trim, condition, and equipment.
Remember that an online estimate is not a guaranteed dealership offer. Actual offers can vary depending on the vehicle's condition, local demand, inspection results, and the dealership's business needs.
It is also useful to request more than one trade-in offer rather than relying on a single estimate.
Step 3: Subtract the vehicle value from the payoff amount
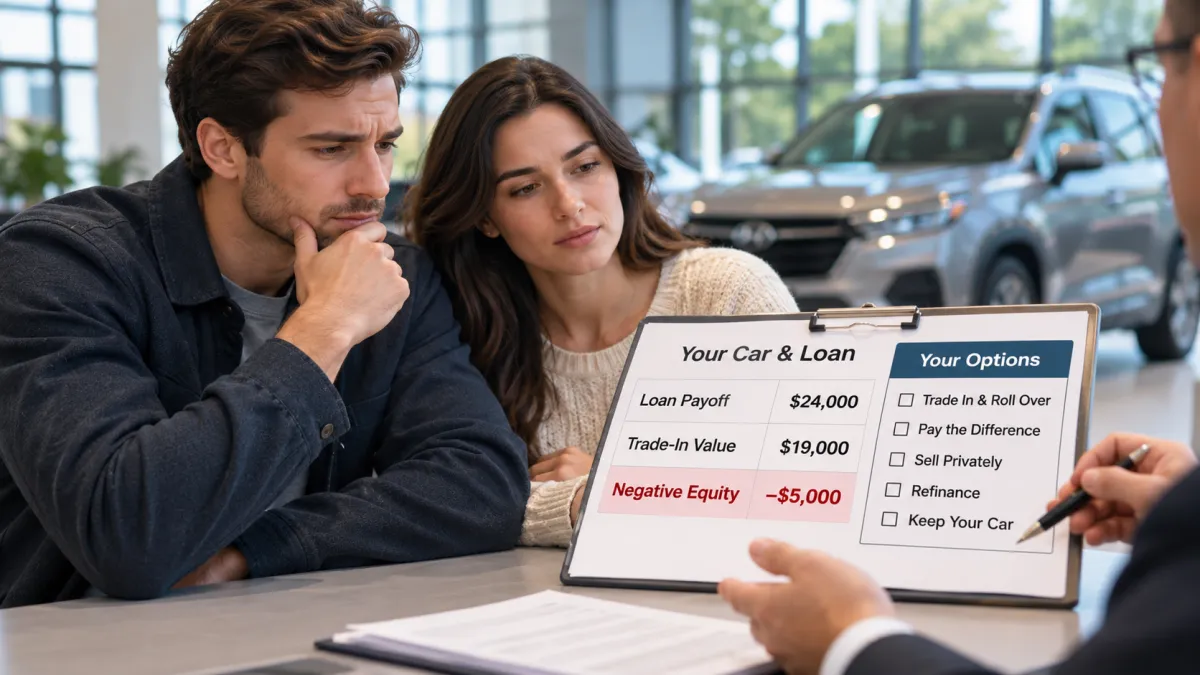
Suppose your lender provides a payoff quote of $20,000, and a dealership offers $16,000 for your vehicle.
| Item | Amount |
|---|---|
| Current loan payoff | $20,000 |
| Trade-in offer | $16,000 |
| Negative equity | $4,000 |
You are $4,000 upside down on the loan.
If another dealership offers $17,000, your shortfall falls to $3,000. That is why comparing offers matters.
Also, keep the distinction between trade-in value and private-sale value in mind. A private buyer may offer more than a dealership, but selling privately can require additional work to handle the lender payoff and title transfer.
Why You May Owe More Than Your Car Is Worth
Negative equity does not necessarily mean you made one major mistake. It can develop gradually as the loan balance and vehicle value change at different rates.
Here are some common reasons.
Your vehicle depreciated faster than you paid down the loan
Most vehicles lose value over time. The amount and speed of depreciation depend on factors such as mileage, condition, age, demand, and vehicle type.
If your car loses value faster than you reduce the loan balance, you can end up owing more than it is worth.
You made a small down payment
A small down payment means you finance a larger portion of the vehicle's purchase price.
If the vehicle's value falls shortly after purchase, the loan balance may remain higher than its market value.
You chose a longer loan term
A longer repayment term spreads payments over more months. This can make the monthly payment easier to manage, but it may also slow the rate at which you build equity, depending on the loan's interest rate and repayment schedule.
If you replace the vehicle before enough principal has been paid down, negative equity may remain.
You rolled previous debt into your current loan
If you previously traded in a vehicle with negative equity and added that balance to your next auto loan, you may have started the new loan owing more than the replacement vehicle was worth.
That debt can continue affecting your finances when you consider another vehicle purchase.
Your vehicle's condition or mileage reduced its value
High mileage, accident history, mechanical problems, cosmetic damage, and heavy wear can reduce what a dealer or private buyer is willing to pay.
Even if your loan balance has decreased, a lower vehicle value can create or increase negative equity.
Can You Trade In a Car With Negative Equity?
Yes, you may be able to trade in a financed vehicle even when its value is lower than the loan payoff.
The dealership will generally need to coordinate the existing loan payoff as part of the transaction. However, you must also decide how the shortfall will be handled.
For example, imagine you want to purchase a replacement vehicle priced at $30,000.
Your existing vehicle has:
-
Loan payoff: $20,000
-
Trade-in offer: $16,000
-
Negative equity: $4,000
If you roll the entire shortfall into the replacement vehicle financing, the starting amount before applicable taxes, fees, and other adjustments could be:
| Item | Amount |
|---|---|
| Replacement vehicle price | $30,000 |
| Negative equity from old vehicle | $4,000 |
| Amount before other adjustments | $34,000 |
This does not mean the new vehicle is worth $34,000. It means you may be borrowing money for both the replacement vehicle and debt left over from the previous one.
The lender must approve the financing arrangement. Approval is not guaranteed, and the lender may consider the loan amount relative to the replacement vehicle's value, your credit, income, existing debts, and other underwriting factors.
Before accepting a trade-in offer, ask the dealership to show exactly how the old loan payoff, trade-in credit, and negative equity appear in the transaction.
What Happens When You Roll Negative Equity Into a New Car Loan?
Rolling negative equity means adding the unpaid shortfall from your existing vehicle to the amount financed for your next vehicle.
This can make replacing your car possible without paying the entire difference upfront. However, it increases the amount you borrow.
Your new loan balance becomes larger
Suppose you purchase a vehicle for $30,000 and have $4,000 in negative equity.
If the lender allows the shortfall to be included in the new financing, you could begin with $34,000 to finance before taxes, fees, and other adjustments.
You are now borrowing more than the replacement vehicle's purchase price.
You may pay more interest
Auto-loan interest is calculated on the amount financed according to the contract's APR and repayment schedule.
When you borrow an additional $4,000, that amount can also generate interest.
This means you may pay interest over several years on debt from a vehicle you no longer own.
Your monthly payment may increase
A larger loan generally creates a higher payment when the APR and repayment term remain the same.
Some buyers try to offset this by choosing a longer loan term. That can reduce the monthly payment, but it may increase the total interest paid and keep the borrower in debt longer.
You may become upside down again
The replacement vehicle can depreciate while you are still paying the loan.
Because your new financing includes debt from the previous vehicle, you may begin with limited or negative equity in the replacement vehicle.
If you need to sell or trade it again before paying down enough of the balance, you could face another negative-equity situation.
For that reason, rolling negative equity into a new loan should be evaluated as a complete financial decision, not simply a way to make a trade-in happen.
Your Options When You Have Negative Equity
You do not have to roll the shortfall into another loan. Compare the following options before deciding.
Option 1: Keep your current car and wait
If your current vehicle is reliable and meets your transportation needs, keeping it may be the simplest way to avoid adding old debt to a new loan.
Continue making payments according to your existing agreement. As you pay down the principal, the difference between your loan balance and the vehicle's value may become smaller.
However, waiting does not guarantee that negative equity will disappear. Your car may continue depreciating, and maintenance or repair costs may increase.
This option is worth considering when:
-
Your vehicle is dependable.
-
Your current payment is manageable.
-
You do not urgently need a replacement.
-
The cost of replacing the vehicle would create financial pressure.
Compare the likely cost of keeping the current vehicle, including maintenance and repairs, with the cost of purchasing another one.
Option 2: Pay the negative equity in cash
If you have enough savings, you can pay the shortfall instead of adding it to your next loan.
Using the earlier example, if your loan payoff is $20,000 and the trade-in offer is $16,000, you would need to cover the $4,000 difference.
This may allow you to start your next auto loan without carrying the previous vehicle's unpaid balance.
However, consider whether paying the shortfall would leave you without enough money for emergencies, insurance, registration, or other essential expenses.
Do not use all your available savings simply to complete a vehicle purchase without considering your wider financial situation.
Option 3: Sell the vehicle privately
A private sale may produce a higher price than a dealership trade-in offer.
For example, a dealer might offer $16,000, while a private buyer may be willing to pay more. If you can obtain a higher selling price, your negative equity could become smaller.
However, selling a vehicle with an outstanding loan requires careful coordination.
You need to:
-
Request an accurate payoff quote from your lender.
-
Determine a realistic private-sale price.
-
Understand how the lender handles payment and lien release.
-
Arrange a secure transaction that satisfies the lender's requirements.
-
Confirm that the loan has been paid and the title can be transferred correctly.
Some lenders have specific procedures for private-party sales involving outstanding loans. Contact the lender before promising a buyer that the title can be transferred immediately.
Private selling also requires time and effort. You may need to handle inquiries, inspections, negotiations, and paperwork.
It is not automatically the better option, particularly if the difference between the private-sale price and dealer offer is small.
Option 4: Trade in the vehicle and roll over the negative equity
If you need another vehicle and cannot pay the shortfall upfront, you may consider rolling the negative equity into the replacement vehicle loan.
This option depends on lender approval and the structure of the transaction.
Before accepting it, check:
-
The full amount being financed.
-
The APR.
-
The loan term.
-
The monthly payment.
-
The total interest over the loan.
-
Any additional products, fees, or charges.
-
Whether the amount financed is reasonable compared with the replacement vehicle's value.
A dealership may focus on making the monthly payment appear affordable. Your responsibility is to understand the full borrowing cost.
Option 5: Refinance your current car loan
If your main problem is an expensive monthly payment or unfavorable interest rate, refinancing may be worth investigating before replacing the vehicle.
Refinancing means replacing your existing loan with a new loan under different terms.
Depending on your circumstances, refinancing may help you obtain a different APR or repayment schedule.
However, it is not a guaranteed solution to negative equity. Lenders have their own eligibility requirements, and the vehicle's value, loan balance, credit profile, and income may affect approval.
Compare the total repayment cost of the new loan with your existing agreement. A lower monthly payment achieved by extending the repayment period may cost more overall.
Is It Better to Sell Privately or Trade In Your Car?
The right choice depends on the amount you can receive, how quickly you need to sell, and how comfortably you can manage the outstanding loan.
| Factor | Dealership trade-in | Private sale |
|---|---|---|
| Potential selling price | May be lower | May be higher |
| Convenience | Usually more convenient | Requires more effort |
| Buyer communication | Handled by dealership | You handle inquiries and negotiations |
| Loan payoff | Dealer may coordinate payoff | You must coordinate with lender and buyer |
| Title and lien process | Usually handled through transaction procedures | Requires careful coordination |
| Time required | Often quicker | Can take longer |
Consider this example:
Your payoff is $20,000.
A dealership offers $16,000, creating $4,000 in negative equity.
A private buyer offers $18,000, reducing the shortfall to $2,000.
In this hypothetical situation, the private sale reduces the amount you need to cover by $2,000.
However, that benefit must be weighed against the work involved and the lender's payoff and title-transfer procedures.
If you cannot safely complete the transaction under your lender's requirements, a higher private-sale offer may not be worth the additional complications.
For more information about the process of selling a financed vehicle, see KnowBrook's guide to buying a used car with an outstanding lien. The article explains the related lien and title considerations involved in a private-party vehicle transaction.
What Does Negative Equity Actually Cost? A Worked Example
A $4,000 shortfall may not sound like a large amount compared with the price of a new vehicle. But financing that amount can make the purchase more expensive over time.
Consider three ways to handle the same negative-equity situation.
Assume:
-
Current loan payoff: $20,000
-
Trade-in value: $16,000
-
Negative equity: $4,000
-
Illustrative financing APR: 8%
-
Illustrative repayment term: 60 months
The 8% APR is a hypothetical assumption for demonstrating the calculation, not a statement of current market rates or a guaranteed lender offer.
Option A: Pay the $4,000 shortfall in cash
You pay the $4,000 difference yourself as part of the transaction.
The previous vehicle's negative equity does not need to be included in the replacement vehicle's financing.
Immediate cost: $4,000.
This avoids paying interest on that $4,000 through the new auto loan, assuming you do not borrow the money elsewhere.
Option B: Roll the $4,000 into the new loan
If a lender approves financing the additional $4,000 at 8% APR for 60 months, the approximate payment attributable to that extra borrowing would be:
| Calculation | Approximate amount |
|---|---|
| Additional amount financed | $4,000 |
| APR | 8% |
| Term | 60 months |
| Additional monthly payment | $81 |
| Total payments over 60 months | $4,867 |
| Interest on the additional $4,000 | $867 |
The figures are rounded estimates based on a standard amortizing loan calculation. They exclude additional fees and other transaction costs.
This shows why rolling negative equity can be expensive. You are not simply transferring $4,000 from one loan to another. You may also pay interest on that amount for five years.
Option C: Keep the current vehicle and delay buying
Instead of trading in the vehicle immediately, you continue making payments on the existing loan.
This avoids adding the $4,000 shortfall to a new loan today.
However, the outcome depends on how quickly you reduce the loan balance and how the vehicle's value changes.
For example, if you pay down the loan while the vehicle's value stays relatively stable, the negative-equity gap may shrink. If the vehicle depreciates or requires expensive repairs, the financial benefit of waiting may be smaller.
Comparing the three choices
| Option | Main financial effect | Main concern |
|---|---|---|
| Pay $4,000 in cash | Avoids financing the shortfall in the new loan | Uses savings immediately |
| Roll $4,000 into new financing | Spreads the shortfall across monthly payments | Adds interest and increases borrowing |
| Keep current vehicle | Avoids taking on replacement-vehicle financing immediately | Continued payments, depreciation, and repair costs |
There is no universally cheapest choice for every buyer. The best decision depends on your savings, vehicle reliability, financing terms, and how urgently you need a replacement.
The important lesson is to compare the total cost rather than choosing an option only because its monthly payment looks smaller.
How to Avoid Negative Equity on Your Next Car
If you decide to replace your vehicle, consider how the next purchase could affect your financial position.
Make a larger down payment when practical
A down payment reduces the amount you need to finance.
If you can comfortably make a down payment without exhausting your emergency savings, it may reduce the chance of starting the new loan with little or negative equity.
Choose a vehicle you can afford comfortably
A less expensive replacement vehicle may make it easier to manage the purchase without carrying a large old-loan balance.
Avoid increasing your borrowing simply to purchase a more expensive model when your current loan already has negative equity.
Compare loan terms carefully
A longer repayment term may reduce your monthly payment, but it can also increase total interest and keep you in debt longer.
Compare the total amount payable across different loan offers instead of focusing only on the monthly figure.
Avoid rolling negative equity into future purchases
If possible, pay off the current shortfall before taking on another vehicle loan.
Repeatedly transferring negative equity from one vehicle to another can create a cycle in which each replacement purchase begins with a larger amount owed.
Compare the actual vehicle price and financing separately
A dealership may discuss the trade-in value, replacement vehicle price, monthly payment, and financing as one combined offer.
Ask for each figure separately so you can understand what you are paying and what you are borrowing.
Negotiating the replacement vehicle price independently from the trade-in can make it easier to compare offers.
What to Check Before Signing a New Car Financing Contract
Before signing, review the entire transaction rather than relying on verbal explanations.
A dealership may say it will pay off your existing vehicle loan. That statement does not necessarily mean it will absorb the negative equity.
The FTC warns consumers to examine how negative equity is handled in the new transaction. The old debt may be included in the replacement loan or offset through other parts of the deal.
Check these details:
-
Old loan payoff: Does the contract show the correct amount needed to satisfy your existing loan?
-
Trade-in allowance: Is the agreed vehicle value shown accurately?
-
Negative equity: Is the shortfall clearly accounted for?
-
Amount financed: Does the amount match the replacement vehicle price, trade-in credit, shortfall, down payment, taxes, and other applicable adjustments?
-
APR: What annual percentage rate are you being charged?
-
Loan term: How many months will you make payments?
-
Total payments: How much will you pay over the full loan?
-
Optional products: Are warranties, service contracts, GAP products, or other add-ons included? Do you want them, and what do they cost?
-
Payment schedule: When is the first payment due, and what is the regular payment amount?
Do not sign documents you do not understand. Ask the dealership to explain any difference between the negotiated vehicle price and the final amount financed.
You can also read KnowBrook's guide on avoiding yo-yo financing after buying a car. It covers a separate financing risk in which a dealership attempts to change financing arrangements after a buyer has taken delivery. Negative equity and conditional financing are different issues, but both make careful contract review important.
How to Confirm Your Previous Car Loan Was Paid Off
Trading in your vehicle does not mean you should stop checking the old loan account.
The dealership may be responsible for sending the payoff, but you should verify that the lender received it and processed the payment.
After the transaction:
-
Keep copies of the signed trade-in and financing documents.
-
Note the payoff amount and the lender's expected processing timeline.
-
Contact your previous lender after approximately one week to check whether the loan has been paid off.
-
Ask whether any remaining balance, interest, or other amount is still due.
-
If the account still shows an unpaid balance, contact the dealership and new lender promptly.
-
Keep records of calls, emails, payment confirmations, and other communications.
The Consumer Financial Protection Bureau advises consumers to contact the previous lender after about one week to confirm the old loan payoff.
If the loan has not been paid, do not assume the issue will resolve itself. Ask the dealership for an explanation and request confirmation of the payment status.
If the problem remains unresolved, you may consider contacting the CFPB, the FTC, or your state attorney general, depending on the nature of the issue.
Should You Buy Another Car Now or Wait?
The decision should be based on your current vehicle's condition, your financial position, and the actual cost of replacing it.
Buying another car now may make sense if your current vehicle is unreliable, you need dependable transportation, and you have a manageable way to cover the negative equity.
Waiting may be more sensible if your current vehicle is dependable, your existing payment is affordable, and replacing it would require adding a large shortfall to a new loan.
Before deciding, compare these factors:
| Decision factor | Buying now may make sense when | Waiting may make sense when |
|---|---|---|
| Vehicle condition | Repairs are frequent or reliability is a serious concern | The car remains dependable |
| Negative equity | You can pay the shortfall or manage the financing cost | The shortfall is large |
| Savings | You can cover the difference comfortably | Paying the shortfall would use most of your savings |
| New loan | The full repayment cost is manageable | The new loan would stretch your budget |
| Transportation needs | You need a replacement vehicle soon | Your current vehicle meets your needs |
Also consider the cost of keeping the current vehicle. If it needs substantial repairs, compare those expected costs with the replacement vehicle's purchase price, insurance, financing, and maintenance expenses.
Do not assume that replacing the car will automatically improve your financial situation. A new vehicle may solve a transportation problem while creating a larger debt problem.
Conclusion
Buying another car while you have negative equity is possible, but the unpaid balance from your current loan must be handled as part of the transaction.
Start by requesting an accurate payoff quote and comparing it with realistic vehicle offers. Then evaluate whether paying the shortfall in cash, selling privately, refinancing, keeping your current car, or rolling the balance into a new loan makes the most financial sense.
If you decide to finance the negative equity, understand how much it adds to your new loan and how much additional interest you may pay. Review the contract carefully, and confirm that your previous lender receives the full payoff.
The most important decision is not simply whether you can get approved for another car. It is whether replacing your vehicle now leaves you with a loan and monthly payment you can comfortably manage without carrying unnecessary debt into your next purchase.
Frequently asked questions
1. Does a dealer's promise to pay off my old car loan mean I no longer owe the negative equity?
No. A dealer's promise to pay off your existing loan does not necessarily mean the dealership absorbs the negative equity. The difference between your loan payoff and the vehicle's trade-in value may be included in your new financing or accounted for through your down payment. Review the new contract carefully and check the amount financed before signing.
2. Does GAP insurance cover negative equity when I trade in my car?
Generally, no. Guaranteed Asset Protection (GAP) coverage is designed to help cover a qualifying difference between your outstanding loan balance and your vehicle insurance payout after a covered theft or total loss. It is not normally designed to pay negative equity during an ordinary trade-in. Check your specific GAP agreement for coverage limits and exclusions.
3. Can I refinance my current car loan instead of trading in my vehicle?
Possibly. Refinancing may help if you qualify for a lower interest rate or more manageable payment. However, approval and available terms depend on factors such as your credit, vehicle value, loan balance, and lender requirements. Compare the total interest and repayment cost, not just the monthly payment, before deciding.
4. Can negative equity prevent me from getting approved for another car loan?
It can make approval more difficult because rolling the shortfall into a new loan increases the amount you want to borrow. Lenders consider factors such as credit history, income, existing debt, vehicle value, and the proposed loan terms. Negative equity does not automatically mean every lender will reject your application.
5. How long should I wait before contacting my old lender after trading in a car?
The Consumer Financial Protection Bureau recommends contacting your previous lender after approximately one week to check whether the old loan has been paid off. If the balance remains, contact the dealership and new lender promptly to clarify the payment status and resolve the issue.
6. Can I trade in a car with negative equity if I have bad credit?
You may be able to, but approval can be more challenging. A lender may be concerned about the larger loan balance created by adding negative equity to the replacement vehicle financing. Consider reducing the shortfall, making a down payment, choosing a less expensive vehicle, or waiting until your loan balance improves.
Olivia Bennett writes practical automotive content covering car buying, ownership costs, maintenance, vehicle features, reliability, and everyday driving decisions. Her work focuses on helping readers understand automoti...