Does Renters Insurance Cover Roommates?
Learn when renters insurance covers roommates, whose belongings and liability may be protected, whether roommates can share a policy, and what to check with an insurer before relying on someone else’s coverage.
In this article
- Does Renters Insurance Cover Roommates Automatically?
- What Does Renters Insurance Usually Cover?
- Personal belongings
- Personal liability
- Additional living expenses
- What renters insurance generally does not replace
- Can Roommates Share One Renters Insurance Policy?
- Shared policy versus separate policies
- Does Your Roommate's Policy Cover Your Belongings?
- Your roommate owns the living room furniture
- You both contribute to a shared purchase
- Your personal belongings are damaged in a covered event
- Does Renters Insurance Cover a Roommate's Liability?
- How to Verify Whether You Are Covered
- Step 1: Review the declarations page
- Step 2: Read the definition of an insured person
- Step 3: Check personal property coverage and limits
- Step 4: Confirm liability coverage
- Step 5: Ask about exclusions, deductibles, and endorsements
- Step 6: Get confirmation in writing
- What Happens When a Roommate Moves In or Out?
- When a new roommate moves in
- When a roommate moves out
- When roommates replace shared belongings
- Common Mistakes Roommates Should Avoid
- Budgeting for Renters Insurance With Roommates
- Conclusion
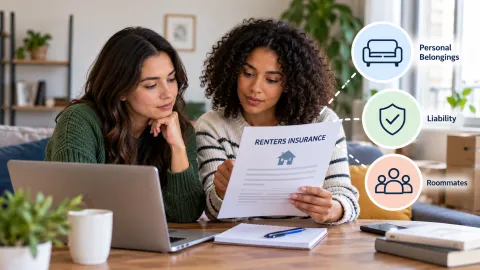
Renters insurance does not automatically cover everyone who lives in the same apartment or rental home. Whether a roommate is protected depends on the policy’s terms, who is named or otherwise qualifies as an insured, and the insurance company’s eligibility rules.
This matters when roommates share rent, furniture, utilities, and other household expenses. One person may purchase a renters insurance policy and assume that everyone in the apartment is protected. But sharing an address does not necessarily mean sharing insurance coverage.
For many unrelated roommates, separate renters insurance policies can be a straightforward way to maintain individual protection. Some insurers may offer options for covering more than one person under a policy, but eligibility and coverage terms vary.
Before relying on a roommate’s insurance, determine whose belongings are covered, who receives liability protection, and what happens if one person moves out. Understanding these details can help you choose an appropriate arrangement and avoid assumptions when a covered loss occurs.
Does Renters Insurance Cover Roommates Automatically?
No. A roommate is not automatically covered simply because they live with someone who has renters insurance.
A renters insurance policy identifies the people who qualify for coverage and explains which property, losses, and liabilities the insurer may cover. The declarations page, policy definitions, exclusions, and endorsements all matter when determining who is protected.
Consider two people renting an apartment together. One roommate purchases a policy to protect their belongings and personal liability. The second roommate contributes to the rent and utilities but is not listed on the policy.
The second roommate should not assume that the policy covers their laptop, clothing, furniture, or personal liability. They need to confirm whether they qualify as an insured under the actual policy. If they do not, they may need their own policy or another arrangement approved by the insurer.
There are three important questions to distinguish:
-
Who is insured? This determines which people qualify for protection under the policy.
-
What is covered? This identifies the types of property, losses, and liabilities that may qualify.
-
What are the limits and exclusions? These determine how much protection may be available and which situations are excluded.
Even when two roommates can share a policy, that does not necessarily mean every possession or every liability claim is covered. The exact terms still matter.
What Does Renters Insurance Usually Cover?
Understanding the main types of renters insurance coverage makes it easier to evaluate whether a roommate needs separate protection.
Personal belongings
Personal property coverage can help pay to repair or replace eligible belongings damaged or lost in a covered event, subject to the policy's terms and limits.
Common examples of personal belongings include:
-
Clothing and shoes
-
Computers, phones, and other electronics
-
Furniture and household furnishings
-
Kitchen equipment and appliances owned by the renter
-
Books, sporting equipment, and personal accessories
Coverage is not automatic for every type of loss. The event must qualify under the policy, and exclusions, deductibles, special limits, and valuation rules may affect payment.
For roommates, the key issue is whose belongings qualify for coverage. If one roommate owns a television and another owns a computer, they should not assume that a policy purchased by either person protects both items.
Keep receipts, photographs, or an inventory of valuable possessions when practical. These records can help establish ownership and document what was lost if a claim becomes necessary.
Personal liability
Personal liability coverage may help protect an insured person financially if they are legally responsible for certain covered injuries or property damage to others. The policy's exclusions, limits, and conditions determine whether a particular claim qualifies.
For example, imagine that a renter accidentally causes damage to another person's property. Whether their renters insurance responds depends on the circumstances, the insured person's status, and the policy terms.
Roommates should pay particular attention to this distinction: a person who is not covered by another roommate's policy should not assume they have that policy's liability protection. Each roommate should confirm their own coverage needs with the insurer.
Liability coverage is also different from coverage for damage to a roommate's own belongings. A claim involving one roommate's damaged property may be handled differently from a claim involving an injury or damage to someone else's property.
Additional living expenses
Some renters insurance policies include additional living expenses coverage for eligible extra costs when a covered loss makes the rental home uninhabitable.
Depending on the policy and circumstances, this could help with certain temporary housing or related additional expenses. Coverage is subject to policy limits, qualifying events, and other conditions.
Roommates should not assume that one person's policy will pay additional living expenses for everyone in the apartment. They should ask the insurer how the policy treats each person and which expenses may qualify.
What renters insurance generally does not replace
Renters insurance is not a guarantee against every loss. A policy may exclude certain events, impose special limits, or require specific conditions to be met.
It also does not generally replace the landlord's property insurance. The landlord's policy typically protects the landlord's property interests, while a tenant's renters insurance addresses the tenant's own covered belongings and liability.
Understanding these distinctions is important before deciding whether one roommate's policy is enough for the household.
Can Roommates Share One Renters Insurance Policy?
Sometimes, but it depends on the insurance company and the policy. There is no universal rule that every insurer must allow unrelated roommates to share a policy, and there is no universal rule that every shared arrangement is prohibited.
Some insurers may permit more than one eligible person to be insured under a policy. Others may restrict eligibility or have specific requirements for people living together. The policy's wording determines who qualifies for coverage.
Before choosing a shared policy, ask the insurer to confirm:
-
Whether unrelated roommates are eligible to share a policy.
-
Which people must be named or otherwise qualify as insureds.
-
Whether each roommate's personal belongings are covered.
-
How personal liability coverage applies to each roommate.
-
Whether coverage limits are shared or apply differently to different insureds.
-
What happens when a roommate moves in or leaves.
-
Whether changes must be reported or documented.
Request written confirmation when possible. A general statement that roommates can share insurance may not answer whether a particular person's belongings and liability are protected.
Shared policy versus separate policies
Both arrangements may be worth considering, but their suitability depends on insurer eligibility, the roommates' needs, and the policy terms.
| Consideration | Shared policy | Separate policies |
|---|---|---|
| Eligibility | The insurer must allow the arrangement and confirm who qualifies. | Each roommate must qualify for their own policy. |
| Personal belongings | Confirm whose possessions are covered and how limits apply. | Each person can review coverage for their own belongings. |
| Liability protection | Confirm how coverage applies to each insured person. | Each person has their own policy terms and limits. |
| Moving out | Changes may require contacting the insurer and reviewing the policy. | Each person can manage their own policy, subject to its terms. |
| Household administration | May involve coordinating policy details and changes. | Each roommate manages their own insurance arrangements. |
| Cost | Depends on the insurer's quote and the coverage provided. | Depends on each person's quote and selected coverage. |
Do not assume that a shared policy is automatically cheaper or that separate policies are always more expensive. Obtain quotes for eligible options and compare the coverage, deductibles, limits, and conditions—not just the premiums.
For many unrelated roommates, separate policies can make it easier to keep coverage arrangements distinct. However, the right decision depends on the available options and each person's circumstances.
Does Your Roommate's Policy Cover Your Belongings?
The answer depends on whether you qualify for coverage under that policy and how it treats personal property.
Living together, splitting household bills, or jointly signing a lease does not by itself establish that your belongings are insured under another person's policy.
Consider a few common situations.
Your roommate owns the living room furniture
Suppose one roommate buys a sofa, television, and coffee table. The other roommate purchases a separate computer and bedroom furniture.
If the first roommate has renters insurance, the second should not assume their own belongings are covered under that policy. The first roommate should also verify how the policy treats property owned by someone else and whether the second roommate qualifies as an insured.
Ownership records and receipts can help document which person owns each item. This is particularly useful when roommates purchase furniture together or transfer belongings between them.
You both contribute to a shared purchase
Roommates sometimes split the cost of a television, couch, kitchen appliance, or other household item.
Joint payment does not automatically determine how an insurance claim will be handled. The policy terms, ownership details, insured status, and circumstances of the loss may all matter.
Before relying on insurance for shared purchases, ask the insurer how jointly owned property is treated. Keep a record of the purchase, each person's contribution, and any agreement about ownership.
Your personal belongings are damaged in a covered event
Imagine that a covered event damages belongings in the apartment. One roommate has a renters insurance policy, while the other does not.
The uninsured roommate should not assume the insured roommate's policy will pay for their losses. Whether a particular item qualifies for coverage depends on the policy and the person's status under it.
The insured roommate should also avoid promising that the policy will cover someone else's possessions before checking with the insurer.
The practical lesson is simple: identify the people insured and the property covered before a loss happens, rather than trying to resolve these questions during a claim.
Does Renters Insurance Cover a Roommate's Liability?
Not automatically. A roommate's liability protection depends on whether that person qualifies as an insured and whether the particular claim falls within the policy's coverage.
Personal liability coverage generally addresses certain covered situations in which an insured person is legally responsible for injury to another person or damage to another person's property. It is not a general guarantee that the insurer will pay for every accident involving people in the household.
For example, imagine that a roommate accidentally damages a visitor's property. The person who caused the damage should not assume that another tenant's policy will protect them. They need to verify their own insured status and the policy's terms.
It is also important to distinguish between liability involving someone outside the household and a disagreement between roommates over damaged belongings. Those situations may raise different coverage questions, and the policy's wording controls.
If you are considering a shared policy, ask the insurer to explain how liability coverage applies to each roommate. Do not rely solely on a summary of the policy or on the fact that the insurer has accepted another person's application.
How to Verify Whether You Are Covered
You do not need to guess about coverage. You can review the policy documents and ask the insurer to clarify any uncertainty before relying on the policy.
Step 1: Review the declarations page
The declarations page summarizes key information about the policy, such as the named insured, coverage types, limits, and policy period.
Check the names listed and compare them with the people who expect to be covered. However, do not rely on the declarations page alone: the full policy may contain definitions, exclusions, and endorsements that affect eligibility.
If your name does not appear, ask the insurer whether you qualify as an insured under any applicable policy provision. Do not assume that living at the insured address is sufficient.
Step 2: Read the definition of an insured person
The policy's definitions section explains who qualifies as an insured. The wording can differ among policies, so a general rule from another insurer may not apply to your situation.
Look for language relevant to roommates, household members, spouses, domestic partners, and other people living at the residence. If the wording is unclear, ask the insurer to explain how it applies to your household.
Do not assume that an unrelated roommate is treated the same as a spouse or domestic partner. The relevant definitions and eligibility requirements must be checked.
Step 3: Check personal property coverage and limits
Confirm whether the policy covers the belongings you want to protect and whether any limits or exclusions could affect them.
Ask about valuable electronics, shared furniture, and items owned jointly with another person if those are relevant to your household. Also ask how the policy handles ownership and proof of loss.
A policy's overall personal property limit does not, by itself, establish that every roommate's belongings qualify.
Step 4: Confirm liability coverage
Ask whether you are insured for personal liability under the policy and what conditions apply. If you are considering a shared policy, request a clear explanation of how the insurer treats each roommate.
Do not assume that being listed as an additional household member, paying part of the premium, or contributing to rent is enough to establish coverage.
Step 5: Ask about exclusions, deductibles, and endorsements
Even when a person qualifies as an insured, the policy may not cover every event or every item.
Review the exclusions and deductible, along with any endorsements that change the standard policy terms. Ask the insurer to explain provisions that could affect your particular situation.
Step 6: Get confirmation in writing
Contact the insurance company or agent and describe your household accurately. Explain whether you are unrelated roommates, whether you share belongings, and whether one person already has a policy.
Ask the insurer to confirm who qualifies as insured, whose property is covered, how liability protection applies, and what changes would be required if a roommate moves out.
Keep the written response with your insurance documents. If the insurer recommends a policy change or separate policies, review the terms before deciding.
What Happens When a Roommate Moves In or Out?
A change in household membership can affect the insurance arrangement, so it is worth reviewing the policy whenever someone moves in or leaves.
When a new roommate moves in
Do not assume that a new roommate becomes covered when they receive the keys or begin paying rent.
The existing policyholder should contact the insurer to explain the change and determine whether the new roommate can be added or otherwise qualifies for coverage. If the insurer does not permit the arrangement, the new roommate may need a separate policy.
The incoming roommate should independently verify their coverage rather than relying only on verbal assurances from the existing tenant.
When a roommate moves out
If a policy covers more than one eligible person, ask the insurer how removing a roommate affects the policy and any remaining coverage. The departing roommate should also verify whether they need a new policy for their belongings and liability at their next residence.
A move may change the insured address, household composition, or other policy details. Report relevant changes as required by the policy and the insurer's instructions.
When roommates replace shared belongings
Moving out often involves dividing furniture, electronics, kitchen items, and other shared purchases.
Update ownership records where appropriate and make sure each person understands which belongings they are taking. If the roommates have separate policies, each should confirm that their policy reflects their new living arrangement and coverage needs.
A brief insurance review during the move can help prevent confusion about who is protected after the household changes.
Common Mistakes Roommates Should Avoid
Several assumptions can create unnecessary uncertainty when roommates rely on insurance.
Assuming the address determines coverage. Sharing an apartment does not automatically make every resident an insured under the same policy.
Assuming one premium protects everyone. Paying rent or contributing to an insurance premium does not establish that every roommate qualifies for coverage.
Confusing property coverage with liability coverage. A policy's treatment of personal belongings may differ from its treatment of liability claims. Verify both separately.
Relying on another insurer's rules. An online article explaining one company's approach does not establish the eligibility rules of every insurer.
Ignoring policy limits and exclusions. A person may qualify as an insured while particular property or losses remain subject to limitations or exclusions.
Failing to report household changes. A new roommate or a move-out may require the insurer to review or update the policy.
Waiting until a loss occurs. Sorting out insured status after a fire, theft, or liability incident can be more difficult than confirming the arrangement beforehand.
Avoiding these mistakes starts with reviewing the actual policy and asking direct questions about the household's circumstances.
Budgeting for Renters Insurance With Roommates
Insurance is one of the recurring expenses to consider when comparing the total cost of renting. The premium is only one part of the decision; the coverage provided, deductible, limits, and eligibility rules also matter.
When comparing arrangements, obtain quotes for the options available to your household. A shared arrangement, if permitted, should be evaluated against separate policies based on what each person would actually receive.
Consider the following factors:
-
Premium: What does each eligible arrangement cost?
-
Deductible: How much might you have to pay toward a covered claim?
-
Personal property limits: Are the limits appropriate for the belongings you need to protect?
-
Liability limits: Does the policy provide the level of protection you want?
-
Exclusions and special limits: Are there restrictions that matter for your possessions or circumstances?
-
Policy administration: How will you manage changes if a roommate moves in or out?
Do not choose a policy based on premium alone. A lower price is not necessarily a better value if the arrangement does not provide the coverage you need.
For more context when calculating housing expenses, KnowBrook's guide on how to compare apartment costs beyond the advertised rent explains why renters should consider recurring expenses in addition to the listed rent.
Conclusion
Renters insurance does not automatically cover roommates simply because they share an apartment. Coverage depends on the policy's definitions, who qualifies as an insured, the property being protected, and the insurer's eligibility rules.
Some insurers may allow eligible roommates to share a policy, while others may require or offer different arrangements. Separate policies can be a practical option for unrelated roommates who want to manage their coverage individually, but the right choice depends on the available terms and each person's needs.
Before relying on someone else's insurance, review the declarations page and policy wording, confirm personal property and liability coverage, and ask the insurer to explain how the policy applies to every roommate. Get confirmation in writing when possible, and revisit the arrangement whenever someone moves in or out.
The most important step is to verify coverage before a loss occurs. Knowing exactly who is insured—and what the policy actually protects—is more reliable than assuming that sharing a home means sharing insurance.
Frequently asked questions
1. Can a landlord require each roommate to have renters insurance?
A landlord may include renters insurance requirements in a lease, subject to applicable state and local law. Review your lease to see what it requires, including whether each roommate must maintain a separate policy or meet other insurance conditions. Ask the landlord for clarification if the wording is unclear.
2. Can an insurer add an unrelated roommate to an existing renters insurance policy?
Possibly, depending on the insurer’s eligibility rules and policy terms. Do not assume an unrelated roommate can be added or that adding someone automatically protects all their belongings and liability. Contact the insurer and request confirmation of who will be insured and what coverage applies.
3. Are spouses or domestic partners treated differently from unrelated roommates?
They may be treated differently under some policies, depending on policy definitions and the insurer’s rules. Marriage, domestic partnership, or sharing an address does not establish the exact coverage by itself. Check the policy language and confirm the situation with the insurer.
4. Does a landlord’s insurance cover a tenant’s belongings?
Generally, a landlord’s insurance protects the landlord’s property interests rather than a tenant’s personal belongings or personal liability. Renters should check their own insurance needs instead of assuming the landlord’s policy will cover their possessions.
5. What documents should renters check to confirm coverage?
Review the declarations page, the policy’s definitions of an insured person, coverage limits, exclusions, and applicable endorsements. Confirm with the insurer whether each roommate is covered, whose belongings are included, and how liability coverage applies. Keep written confirmation for reference.

Daniel Brooks writes practical content about personal finance, budgeting, saving, credit, banking, taxes, and everyday money decisions. His work focuses on explaining financial topics in straightforward language and help...