What Is Net Worth? How to Calculate Your Assets Minus Your Debts
Learn what net worth means, how to calculate it using your assets and liabilities, what counts toward the calculation, and how to interpret your result.
In this article
- What Is Net Worth?
- The Net Worth Formula
- What Counts as an Asset?
- Cash and Bank Accounts
- Investments
- Retirement Accounts
- Real Estate
- Vehicles and Other Property
- What Counts as a Liability?
- Mortgages
- Auto Loans
- Student Loans
- Credit-Card Debt
- How to Calculate Your Net Worth Step by Step
- Step 1: List Your Assets
- Step 2: Determine Current Asset Values
- Step 3: List Your Liabilities
- Step 4: Add Your Total Assets
- Step 5: Add Your Total Liabilities
- Step 6: Subtract Liabilities From Assets
- Why Current Value Matters
- Net Worth Is Not the Same as Cash You Can Spend
- Net Worth vs. Income: What Is the Difference?
- What Does a Positive or Negative Net Worth Mean?
- Why Track Your Net Worth Over Time?
- Common Mistakes When Calculating Net Worth
- Counting the Same Asset Twice
- Using Original Purchase Prices for Everything
- Forgetting Smaller Debts
- Treating Net Worth as Spendable Money
- Comparing Yourself With a Random Benchmark
- Focusing on One Number Instead of the Components
- How Debt Payoff Can Affect Net Worth
- A Simple Way to Keep Your Net-Worth Statement Organized
- The Bottom Line
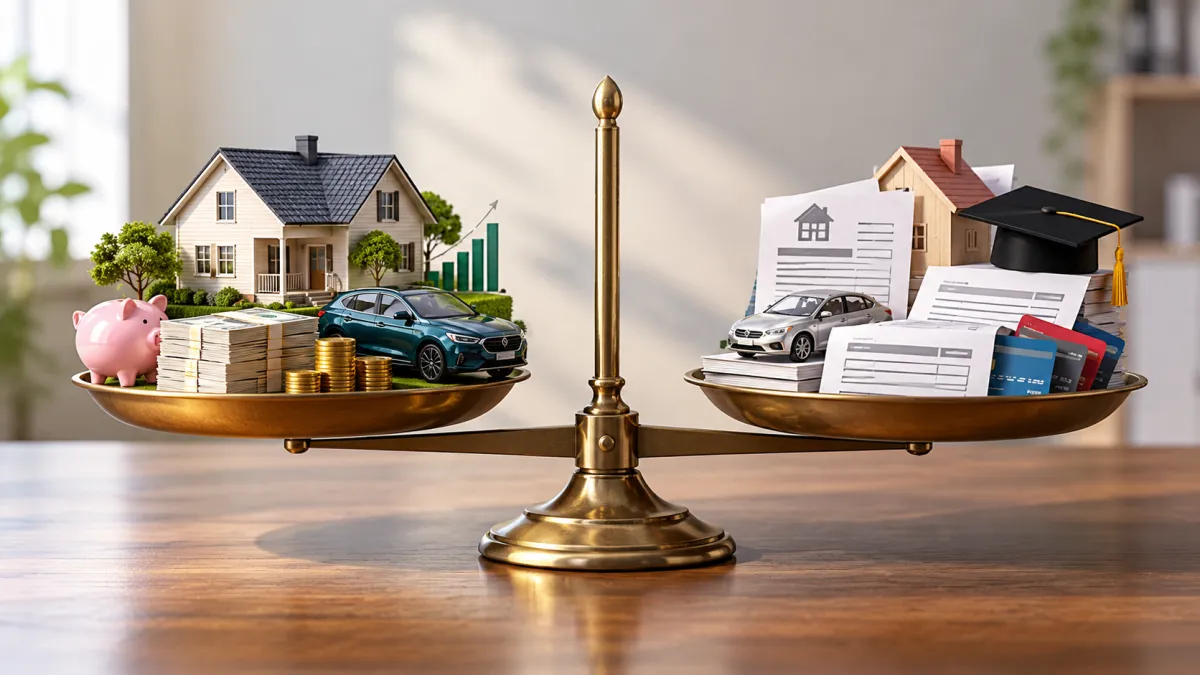
Net worth is a simple way to measure your overall financial position. It represents the value of what you own after subtracting what you owe.
The basic formula is:
Net worth = Total assets − Total liabilities
Your assets can include money in checking and savings accounts, investments, retirement accounts, real estate, and vehicles. Your liabilities can include mortgages, auto loans, student loans, credit-card balances, and other debts.
For example, if your assets are worth $410,000 and your liabilities total $275,000, your net worth is $135,000.
Knowing your net worth can help you understand your financial position beyond your paycheck or bank balance. It can also give you a useful way to track whether your overall finances are improving over time.
What Is Net Worth?
Net worth is the difference between the total value of your assets and the total amount of your liabilities.
In simple terms, it answers one question:
If you added up what you own and subtracted what you owe, what would be left?
A person can have a high income but relatively low net worth if they have substantial debt and few accumulated assets. Someone with a more modest income could have a higher net worth if they have built significant savings, investments, home equity, or other assets while keeping debt under control.
Net worth is therefore different from income.
Income measures money coming in over a period of time. Net worth measures the value of your financial position at a particular point in time.
Your net worth can be positive, zero, or negative.
-
Positive net worth: Your assets are worth more than your liabilities.
-
Zero net worth: Your assets and liabilities are approximately equal.
-
Negative net worth: Your liabilities are greater than your assets.
The number is most useful when treated as a financial snapshot and tracked over time rather than as a judgment about whether someone is financially successful.
The Net Worth Formula
The calculation is straightforward:
Net worth = Assets − Liabilities
Suppose you have:
-
$15,000 in checking and savings
-
$55,000 in retirement accounts
-
$20,000 in investments
-
A home currently valued at $300,000
-
A vehicle currently valued at $20,000
Your total assets would be:
$15,000 + $55,000 + $20,000 + $300,000 + $20,000 = $410,000
Now suppose you owe:
-
$240,000 on a mortgage
-
$12,000 on an auto loan
-
$18,000 in student loans
-
$5,000 in credit-card balances
Your total liabilities would be:
$240,000 + $12,000 + $18,000 + $5,000 = $275,000
Your net worth would be:
$410,000 − $275,000 = $135,000
This is a hypothetical example for demonstrating the calculation. It is not a recommended net-worth target or a benchmark for a particular household.
The same formula works whether the resulting number is positive or negative.
What Counts as an Asset?
An asset is something you own that has measurable financial value.
For a personal net-worth calculation, common assets include financial accounts, investments, real estate, vehicles, and certain other valuable property.
Cash and Bank Accounts
Money held in financial accounts generally counts toward your assets.
This can include:
-
Checking accounts
-
Savings accounts
-
Certificates of deposit
-
Money market accounts
-
Cash on hand
For example, if you have $4,000 in checking and $11,000 in savings, you would generally include $15,000 in your asset total.
If you want to understand how savings accounts work and why the balance can be part of your overall financial position, see KnowBrook's guide to a savings account.
Investments
Investments can also be included in net worth.
Examples include:
-
Stocks
-
Bonds
-
Mutual funds
-
Other investment accounts
For a current net-worth snapshot, the relevant figure is generally the current value of the investment rather than the amount you originally paid for it.
Investment values can change from day to day, so your net worth can change even when you have not deposited or withdrawn money from the account.
Retirement Accounts
Retirement accounts are generally part of personal net worth.
Examples can include:
-
401(k) accounts
-
Individual retirement accounts
-
Other retirement investment accounts
The fact that money is intended for retirement does not make it irrelevant to your overall net worth. It is still an asset you own.
However, net worth should not be confused with money that is immediately available to spend. Some assets may be difficult or costly to access quickly, and retirement accounts are designed for long-term financial purposes.
Real Estate
Real estate can be one of the largest assets in a household's net-worth calculation.
This can include:
-
A primary residence
-
A vacation home
-
Rental property
-
Other real estate you own
For a current calculation, use a reasonable estimate of the property's current value rather than automatically using the original purchase price.
If a home is worth $350,000 and you still owe $250,000 on the mortgage, you do not normally count the full $350,000 as money you have available to spend. Instead, the home is an asset and the mortgage is a liability.
The difference between the home's value and the mortgage balance contributes to your net worth.
Vehicles and Other Property
Vehicles can also be assets.
If your car is currently worth about $20,000, that value can be included in your assets. If you still owe $12,000 on an auto loan, the $12,000 balance is included separately as a liability.
Depending on your circumstances, other property with meaningful measurable value may also be included. The goal is to create a useful picture of what you own rather than to assign a dollar value to every ordinary household possession.
What Counts as a Liability?
A liability is an amount you owe to another party.
Common personal liabilities include:
-
Mortgages
-
Auto loans
-
Student loans
-
Credit-card balances
-
Personal loans
-
Other outstanding debts
The key question is simple: Do you owe this amount?
If the answer is yes and the amount represents a financial obligation, it may belong in your liabilities when calculating personal net worth.
Mortgages
A mortgage is one of the most common liabilities associated with a household's net worth.
Suppose your home is currently worth $300,000 and your remaining mortgage balance is $240,000.
You would generally record:
Home value: $300,000 asset
Mortgage balance: $240,000 liability
The difference is $60,000 of home equity.
That equity contributes to your net worth, but the entire $300,000 home value is not the same thing as $300,000 of spendable cash.
Auto Loans
The same principle applies to a financed vehicle.
If a vehicle is currently worth $20,000 and you owe $12,000 on the auto loan, you would include both figures:
-
Vehicle: $20,000 asset
-
Auto loan: $12,000 liability
The difference contributes $8,000 to your net worth.
Student Loans
Outstanding student loans are liabilities.
If you owe $18,000 in student loans, that $18,000 belongs in the liability portion of your calculation.
Paying down debt can increase net worth when the liability balance falls, assuming other factors remain unchanged.
Credit-Card Debt
Credit-card balances are also liabilities.
For example, if you have $5,000 in outstanding credit-card balances, that amount reduces your net worth.
If managing credit-card debt is part of your broader financial goals, you can also review KnowBrook's guide to credit card debt.
How to Calculate Your Net Worth Step by Step
You can calculate your net worth with a simple list of your assets and liabilities.
Step 1: List Your Assets
Start by writing down the assets you want to include.
You might organize them into categories such as:
| Asset category | Example |
|---|---|
| Checking and savings | $15,000 |
| Retirement accounts | $55,000 |
| Investments | $20,000 |
| Home | $300,000 |
| Vehicle | $20,000 |
| Total assets | $410,000 |
The numbers above are the same hypothetical figures used in the earlier example.
The important part is to avoid counting the same asset twice. For example, money already included in an investment account should not also be listed as cash in a bank account.
Step 2: Determine Current Asset Values
For assets whose values change, use a reasonable current estimate.
Bank accounts are usually straightforward because the account balance provides a current figure.
Investments may be valued using their current account value.
Homes and vehicles require more judgment because their market values can change.
You do not necessarily need a professional appraisal for a basic personal net-worth calculation. The goal is to use a reasonable estimate that gives you a useful snapshot.
Step 3: List Your Liabilities
Next, write down the balances you owe.
For example:
| Liability | Example balance |
|---|---|
| Mortgage | $240,000 |
| Auto loan | $12,000 |
| Student loans | $18,000 |
| Credit cards | $5,000 |
| Total liabilities | $275,000 |
Use the outstanding balance rather than the original amount you borrowed.
If you originally borrowed $300,000 for a mortgage but now owe $240,000, the liability for your current net-worth calculation is the remaining $240,000.
Step 4: Add Your Total Assets
Add the current values of the assets you have listed.
Using the hypothetical example:
Total assets = $410,000
Step 5: Add Your Total Liabilities
Add the current balances of the debts you have listed:
Total liabilities = $275,000
Step 6: Subtract Liabilities From Assets
Now apply the formula:
$410,000 − $275,000 = $135,000
The resulting $135,000 is the hypothetical net worth.
Once you have calculated it, save the result and the underlying figures. That makes it easier to compare your financial position when you calculate it again later.
Why Current Value Matters
One of the easiest ways to make a net-worth calculation less useful is to use outdated values.
Imagine you bought a vehicle several years ago for $30,000. If the vehicle is now worth $18,000, using the original $30,000 purchase price would overstate your current assets.
The same principle applies to real estate and investments.
A home purchased for $250,000 might now be worth more or less than that amount. An investment purchased for $10,000 might now have a different market value.
For a current snapshot, reasonable current values provide a more useful picture than simply copying old purchase prices.
At the same time, estimates do not need to be perfect. If an asset is difficult to value, use a reasonable figure and apply the same approach consistently when you track your net worth over time.
Net Worth Is Not the Same as Cash You Can Spend
A positive net worth does not mean you have that amount sitting in your checking account.
Consider someone who owns a home worth $400,000 but has a large mortgage balance. Much of the person's net worth may be tied to home equity rather than cash.
The same is true of retirement accounts and investments. They can contribute to net worth while serving different purposes and having different levels of accessibility.
This distinction matters when thinking about financial decisions.
A person could have a positive net worth but still have limited cash available for an unexpected expense. Conversely, someone could have substantial cash temporarily while carrying significant debts.
Net worth measures overall financial position. It is not a substitute for looking at cash flow, emergency savings, debt payments, or other parts of your financial situation.
Net Worth vs. Income: What Is the Difference?
Income and net worth answer different financial questions.
Income asks: How much money are you earning or receiving?
Net worth asks: What is the value of what you own after subtracting what you owe?
For example, imagine two people who each earn $80,000 per year.
One person might have accumulated significant retirement savings and investments while keeping debt relatively low. The other might have little saved and substantial debt.
Their incomes are the same, but their net worth could be very different.
Income can affect your ability to save and pay down debt, but it does not determine your net worth by itself.
Similarly, disposable income is a different concept from net worth. KnowBrook's guide to disposable income explains how income available after certain deductions differs from an overall measure of assets minus liabilities.
What Does a Positive or Negative Net Worth Mean?
A positive net worth means your assets are worth more than your liabilities.
For example:
Assets: $250,000
Liabilities: $180,000
Net worth: $70,000
A negative net worth means your liabilities exceed your assets.
For example:
Assets: $80,000
Liabilities: $120,000
Net worth: −$40,000
A negative result does not mean the calculation is wrong. It simply means the total amount owed is greater than the value of the assets included in the calculation.
The number can change as debts are paid down, savings increase, investments change in value, property values change, or other assets and liabilities change.
Why Track Your Net Worth Over Time?
A single net-worth calculation tells you where you stand at one point in time. Repeated calculations can show how that position changes.
For example, you might calculate your net worth once a year and compare:
-
Total assets
-
Total liabilities
-
Retirement balances
-
Investment balances
-
Home value
-
Mortgage balance
-
Other debt balances
-
Overall net worth
This can help reveal changes that are difficult to notice by looking only at a checking-account balance.
Suppose your checking account has stayed relatively stable, but you have been contributing to a retirement account and paying down your mortgage. Your overall net worth may have increased even though your checking balance did not change much.
On the other hand, a decline in investment or property values could reduce net worth even when your income and spending habits remain unchanged.
The purpose of tracking is not to make every month look better than the previous month. Asset values can fluctuate. The longer-term trend is often more useful than any single number.
Common Mistakes When Calculating Net Worth
A few simple mistakes can make the result misleading.
Counting the Same Asset Twice
Make sure each account or asset appears only once.
For example, do not count money in an investment account as both an investment and cash.
Using Original Purchase Prices for Everything
Purchase prices may be outdated. For a current snapshot, use reasonable current values for assets whose values have changed.
Forgetting Smaller Debts
It is easy to remember a mortgage or auto loan while overlooking credit-card balances, student loans, or other outstanding obligations.
A more complete liability list gives you a more useful calculation.
Treating Net Worth as Spendable Money
Net worth can include homes, retirement accounts, investments, and vehicles. Those assets may not be immediately available as cash.
A positive net worth therefore does not automatically mean you have the same amount available to spend.
Comparing Yourself With a Random Benchmark
A net-worth number has to be understood in context.
Age, household circumstances, home ownership, education debt, family responsibilities, savings habits, and many other factors can affect a person's financial position.
For a personal financial check, the more useful question is often whether your own financial position is moving in a direction that supports your goals.
Focusing on One Number Instead of the Components
If your net worth changes, look at why.
Did your investment balances change? Did you pay down debt? Did your home value change? Did your savings increase?
Looking at the underlying assets and liabilities can provide more useful information than simply watching the final net-worth number.
How Debt Payoff Can Affect Net Worth
Reducing debt can improve net worth because liabilities are part of the formula.
Suppose you have $50,000 in assets and $30,000 in liabilities. Your net worth is $20,000.
If you pay $5,000 toward debt and nothing else changes, your liabilities fall to $25,000 and your net worth becomes $25,000.
The change is not because paying a debt created a new asset. It is because the amount you owe became smaller.
When choosing a debt-payoff approach, the method you use can depend on your balances, interest rates, cash flow, and personal preferences. KnowBrook's guide to debt payoff methods covers two commonly discussed approaches.
A Simple Way to Keep Your Net-Worth Statement Organized
You do not need a complicated system to track your net worth.
A simple worksheet can contain four columns:
| Category | Item | Current value | Type |
|---|---|---|---|
| Banking | Checking and savings | $15,000 | Asset |
| Retirement | Retirement accounts | $55,000 | Asset |
| Investments | Investment accounts | $20,000 | Asset |
| Real estate | Home | $300,000 | Asset |
| Transportation | Vehicle | $20,000 | Asset |
| Housing debt | Mortgage | $240,000 | Liability |
| Auto debt | Auto loan | $12,000 | Liability |
| Education debt | Student loans | $18,000 | Liability |
| Credit | Credit-card balances | $5,000 | Liability |
At the bottom, calculate total assets, total liabilities, and net worth.
Keeping the underlying figures is useful because it allows you to see what actually changed between one calculation and the next.
The Bottom Line
Net worth is a straightforward measure of your overall financial position:
Net worth = total assets − total liabilities.
Assets can include bank accounts, investments, retirement accounts, real estate, vehicles, and other property with measurable value. Liabilities can include mortgages, auto loans, student loans, credit-card balances, and other debts.
For a useful current snapshot, use reasonable current values for assets rather than automatically relying on original purchase prices. Then subtract your outstanding liabilities.
Most importantly, treat net worth as a financial measurement rather than a score. A single number tells you where you stand at one point in time. Tracking the number and its underlying assets and debts over time can give you a clearer picture of how your overall financial position is changing.
Frequently asked questions
Can you have a negative net worth?
Yes. You have a negative net worth when your total liabilities are greater than the value of your total assets. This can happen when someone has substantial student loans, credit-card debt, an auto loan, or other debts relative to their assets. A negative number is a snapshot of your financial position at that point in time; it does not by itself determine your future financial situation.
How often should you calculate your net worth?
There is no universal requirement to calculate net worth on a particular schedule, but tracking it periodically can help you see how your financial position changes over time. Investor.gov recommends updating a net-worth statement annually.
Should you use the original purchase price or current value of an asset?
For a current net-worth calculation, use a reasonable estimate of the asset's current value rather than automatically using what you originally paid. This is particularly relevant for assets such as homes and vehicles, whose values can change over time.
What if an asset does not have an obvious current value?
Use a reasonable current estimate rather than assuming the original purchase price is still accurate. For assets that are difficult to value, the goal of a personal net-worth calculation is to create a useful snapshot, not necessarily an exact professional appraisal.
Does net worth include everything you own?
Net worth generally includes assets with measurable value, such as money in bank accounts, investments, retirement accounts, real estate, and vehicles, minus your liabilities. Not every possession needs to be assigned a value, particularly when doing a practical personal calculation.
Can your net worth change even if your income does not?
Yes. Net worth can change when asset values rise or fall, when you pay down debt, or when you save or spend money. Income is money received over a period of time, while net worth is a snapshot of assets minus liabilities.

Daniel Brooks writes practical content about personal finance, budgeting, saving, credit, banking, taxes, and everyday money decisions. His work focuses on explaining financial topics in straightforward language and help...