What Is Service Finance Company? How Its Home Improvement Loans Work
Learn what Service Finance Company is, how its home improvement financing works through contractors, and how to compare loan types, APR, monthly payments, and total repayment costs. This guide also explains payment basics, borrower considerations, customer reviews, and alternatives to contractor-arranged financing.
In this article
- What Is Service Finance Company?
- Who Owns Service Finance Company?
- How Does Service Finance Company Home Improvement Financing Work?
- Step 1: Choose a Home Improvement Contractor
- Step 2: Review the Project Estimate
- Step 3: Review the Financing Offer
- Step 4: Submit a Financing Application
- Step 5: Complete the Home Improvement Project
- Step 6: Repay the Loan
- What Types of Financing Does Service Finance Company Offer?
- No-Interest Promotional Financing
- Deferred-Interest Financing
- Long-Term Installment Financing
- Comparing the Financing Types
- How Much Does Service Finance Company Financing Cost?
- Understand the APR
- Consider the Repayment Term
- Evaluate the Total Amount Repaid
- A Hypothetical Financing Example
- What Should Homeowners Check Before Signing a Service Finance Loan?
- 1. The APR and Interest Rate
- 2. The Monthly Payment
- 3. The Repayment Term
- 4. The Total Repayment Amount
- 5. Fees and Other Conditions
- 6. The Contractor's Written Agreement
- 7. Whether the Financing Fits Your Budget
- How Do Service Finance Company Payments Work?
- When Do Payments Begin?
- What Happens If a Payment Is Late?
- Is Service Finance Company Legitimate?
- Check the Contractor Separately
- Service Finance Company Reviews: What Should Borrowers Consider?
- Why Customer Reviews Need Context
- How to Use Review Platforms
- Pros and Cons of Service Finance Company Home Improvement Financing
- Service Finance Company vs. Other Home Improvement Financing Options
- Service Finance Company vs. a Personal Loan
- Service Finance Company vs. a Home Equity Loan
- Service Finance Company vs. a HELOC
- Service Finance Company vs. Paying With Savings
- Comparing the Alternatives
- What Happens If There Is a Problem With the Contractor?
- Keep Documentation
- Contact the Appropriate Parties
- Conclusion
Service Finance Company is a consumer financing provider that helps homeowners pay for home improvement projects through loans arranged by participating contractors. Its financing may be offered when a homeowner is planning work such as replacing an HVAC system, installing new windows, repairing a roof, or completing a remodeling project.
Rather than paying the entire project cost upfront, an eligible homeowner may be able to finance the expense and repay it over time. The available financing options, interest rate, payment schedule, and total cost depend on the specific offer and loan agreement.
Service Finance Company is not a home improvement contractor. It provides financing, while the contractor performs the renovation or repair work. Understanding this distinction is important because the financing agreement and the home improvement contract are separate arrangements that can affect a homeowner in different ways.
This guide explains how Service Finance Company works, the types of financing it may offer, how to evaluate the cost of a loan, and what homeowners should consider before accepting contractor-arranged financing.
What Is Service Finance Company?
Service Finance Company LLC is a financing provider focused on home improvement projects. It works with enrolled contractors who offer financing options to customers as part of the home improvement purchasing process.
For example, a homeowner may contact an HVAC contractor to replace an aging heating and cooling system. After the contractor provides an estimate, the homeowner may be offered financing through Service Finance Company.
The homeowner can then review the available loan offer, apply if interested, and evaluate whether the repayment terms fit their budget.
Service Finance Company operates as a sales finance company. Its financing products are generally structured as installment loans rather than revolving credit cards. This means the borrower receives financing for a specific purchase or project and repays it according to a defined loan agreement.
The company offers financing in connection with various home improvement services, including:
-
Heating and air conditioning systems
-
Roofing projects
-
Windows and doors
-
Plumbing improvements
-
Home remodeling
-
Other qualifying residential improvement projects
The exact services and financing options available depend on the participating contractor and the program being offered.
Who Owns Service Finance Company?
Service Finance Company is a subsidiary of Truist Financial Corporation.
Truist announced its acquisition of Service Finance Company in August 2021, and the acquisition was completed on December 6, 2021.
This corporate relationship provides useful context for homeowners researching the company. However, a parent company's name does not automatically determine the interest rate, eligibility, repayment terms, or other conditions of an individual loan.
Borrowers should evaluate the specific financing agreement offered to them rather than relying solely on the company's ownership information.
How Does Service Finance Company Home Improvement Financing Work?
Service Finance Company financing generally begins with a home improvement contractor. The homeowner chooses a project, receives a quote, and may be offered financing options through the contractor's participating financing arrangement.
The process typically follows several stages.
Step 1: Choose a Home Improvement Contractor
Start by identifying a contractor for the project.
The contractor should be qualified to perform the work and should provide a clear description of the proposed improvements. Depending on the project and location, licensing, insurance, permits, and other requirements may apply.
Do not choose a contractor solely because financing is available. The quality of the work, the written estimate, the contractor's reputation, and the project scope are equally important considerations.
Step 2: Review the Project Estimate
The contractor should provide a written estimate that explains the expected project cost.
The estimate may include labor, materials, equipment, installation, and other charges. It should also explain the work being performed and any relevant exclusions.
Before applying for financing, make sure the estimate accurately reflects the project you want.
Step 3: Review the Financing Offer
If the contractor participates in Service Finance Company's financing programs, the contractor may present one or more loan options.
The offer may include information such as:
-
Interest rate or APR
-
Loan amount
-
Repayment term
-
Monthly payment
-
Promotional financing conditions
-
Fees, if applicable
-
Total repayment cost
Not every contractor offers the same financing programs. A homeowner may receive different options depending on the contractor, the project, and the borrower's application.
Step 4: Submit a Financing Application
If you decide to pursue the offer, you may need to submit a credit application.
The lender evaluates the application under its applicable underwriting criteria. Approval is not guaranteed, and the terms offered may differ from the terms advertised by the contractor.
Before proceeding, review the complete loan agreement and understand what you are agreeing to.
Step 5: Complete the Home Improvement Project
After the financing arrangement and project details are finalized, the contractor performs the work according to the home improvement contract.
The project may involve installation, repairs, inspections, or other agreed-upon services.
Keep copies of the estimate, signed contract, financing agreement, payment records, warranties, and communications with the contractor.
Step 6: Repay the Loan
Once the loan is established, the borrower is responsible for making payments according to the loan agreement.
The payment schedule, amount, interest rate, and repayment term are determined by the specific financing arrangement.
A homeowner should not assume that the financing terms remain the same as a promotional offer shown during the initial sales conversation. The signed agreement is the important document to review.
What Types of Financing Does Service Finance Company Offer?
Service Finance Company offers different types of home improvement financing. These may include promotional financing and longer-term installment options.
The differences between these offers can significantly affect how much a homeowner ultimately pays.
No-Interest Promotional Financing
Some offers may provide a promotional period during which interest is not charged, subject to the terms of the agreement.
These offers can be attractive to homeowners who expect to manage the required payments within the promotional period.
However, the phrase "no interest" should be evaluated carefully. The homeowner needs to understand the length of the promotion, the required payment amount, and any conditions attached to the offer.
The exact structure of the promotion matters more than the promotional label.
Deferred-Interest Financing
Deferred-interest financing is different from a straightforward no-interest loan.
Under a deferred-interest arrangement, interest may accrue during a promotional period but may not be charged if the borrower satisfies the conditions specified in the agreement.
If the required conditions are not met, interest may become payable under the agreement. This can increase the total cost of financing.
A homeowner considering deferred-interest financing should carefully examine the promotional expiration date, payment requirements, and applicable interest terms.
Do not assume that making the regular minimum payment will necessarily satisfy every promotional condition.
Long-Term Installment Financing
Long-term installment loans allow borrowers to repay a home improvement expense over an extended period.
These loans generally involve a defined loan amount, repayment term, and scheduled payments.
A longer repayment term can reduce the required monthly payment compared with a shorter term for the same amount and interest rate. However, extending repayment can also increase the total interest paid.
For homeowners considering expensive improvements, long-term financing may help spread the cost across multiple years. The trade-off is that the borrower may remain responsible for the debt long after the project is completed.
Comparing the Financing Types
| Financing Type | Main Feature | Important Consideration |
|---|---|---|
| No-interest promotional financing | Interest may not be charged during the specified promotion | Understand the payment requirements and promotional conditions |
| Deferred-interest financing | Interest may accrue during the promotional period | Failure to meet conditions may increase the cost |
| Long-term installment loan | Repayment is spread over a defined term | A longer term may increase total interest paid |
The availability of each option depends on the contractor's program and the borrower's specific offer.
How Much Does Service Finance Company Financing Cost?
There is no single universal cost for a Service Finance Company loan.
The amount a homeowner pays depends on several factors, including the financed project amount, APR, repayment term, and any applicable fees or promotional conditions.
The monthly payment alone is not enough to determine whether a financing offer is affordable.
Understand the APR
APR, or annual percentage rate, is an important measure when comparing borrowing costs.
It helps borrowers evaluate the cost of credit beyond simply looking at the monthly payment. The APR and applicable disclosures should be reviewed alongside the repayment term and total repayment amount.
A lower monthly payment does not necessarily mean a cheaper loan.
Consider the Repayment Term
The repayment term determines how long the borrower has to repay the loan.
For example, a hypothetical homeowner financing a $12,000 project might compare two offers:
-
A shorter repayment term with a higher monthly payment
-
A longer repayment term with a lower monthly payment
The longer-term option may be easier to fit into a monthly budget. However, if interest applies, extending the term can increase the total interest paid.
The homeowner should compare both the monthly obligation and the overall repayment cost.
Evaluate the Total Amount Repaid
The total amount repaid is one of the most useful figures to consider.
A homeowner should compare:
-
The original amount financed
-
The total scheduled payments
-
Any applicable fees
-
Any interest that may be charged
-
The total cost under the offer's conditions
This allows the borrower to understand how much the financing adds to the cost of the home improvement project.
A Hypothetical Financing Example
Suppose a homeowner needs a $10,000 home improvement project.
The homeowner receives two hypothetical offers:
| Feature | Offer A | Offer B |
|---|---|---|
| Amount financed | $10,000 | $10,000 |
| Repayment term | Shorter | Longer |
| Monthly payment | Higher | Lower |
| Total interest | Potentially lower | Potentially higher |
This example does not represent an actual Service Finance Company offer. It illustrates why homeowners should not compare financing options using monthly payment alone.
The actual cost must be calculated using the interest rate, term, payment schedule, and conditions of the specific loan.
What Should Homeowners Check Before Signing a Service Finance Loan?
A home improvement financing agreement is a financial commitment. Before accepting an offer, review the loan terms carefully.
1. The APR and Interest Rate
Identify the applicable APR and interest rate.
If the offer includes a promotional period, understand whether it is no-interest or deferred-interest financing. Make sure you understand how interest is calculated and when it may apply.
2. The Monthly Payment
Confirm the required monthly payment and whether it could change under the terms of the agreement.
A payment that appears manageable during the sales process may become difficult if household expenses increase.
3. The Repayment Term
Check how long the loan will remain outstanding if you make the scheduled payments.
A longer term can make payments more manageable, but it can also extend the period during which you are responsible for the debt.
4. The Total Repayment Amount
Review the total amount you are expected to repay.
If this figure is not clearly presented in the offer, ask for an explanation before signing.
5. Fees and Other Conditions
Review any fees that may apply under the agreement. For example, late fees may be subject to the contract and applicable state requirements.
Do not assume that fees are identical for all borrowers or all financing programs.
6. The Contractor's Written Agreement
The financing agreement is not a substitute for the home improvement contract.
The home improvement contract should clearly explain:
-
The work being performed
-
The materials or equipment being installed
-
The expected project cost
-
The payment schedule
-
The project's scope
-
Any applicable warranty
-
Relevant completion expectations
Avoid signing blank or incomplete documents.
7. Whether the Financing Fits Your Budget
A home improvement loan should be evaluated in the context of your other financial obligations.
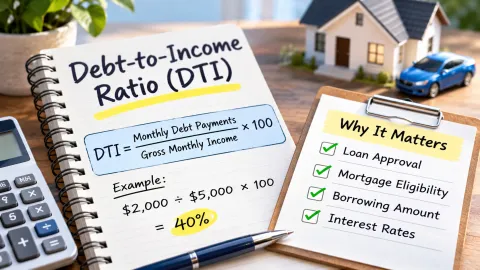
Your debt-to-income ratio can help you understand how much of your income is already committed to debt payments. You can learn more about understanding your debt-to-income ratio.
The goal is not simply to obtain financing. It is to choose an arrangement that you can reasonably manage over the repayment period.
How Do Service Finance Company Payments Work?
Service Finance Company's FAQ describes its financing as installment loans with scheduled repayment obligations.
The company's FAQ also identifies payment methods such as checks, ACH payments, money orders, and cashier's checks. It states that credit and debit cards are not accepted as payment methods.
Payment details should be confirmed using the current official information and the borrower's loan agreement.
When Do Payments Begin?
Service Finance Company's FAQ states that the first payment is due 30 days after installation is complete.
Homeowners should confirm the applicable payment date and schedule in their own agreement and account information.
It is important to understand the repayment schedule before the project begins so that payments do not come as a surprise.
What Happens If a Payment Is Late?
Late payments may result in fees or other consequences under the loan agreement.
The applicable terms can vary, and late-fee rules may depend on the borrower's state and contract.
A borrower who anticipates difficulty making a payment should contact the loan servicer as early as possible to understand available options. Ignoring a payment problem can make it more difficult to manage.
Is Service Finance Company Legitimate?
Service Finance Company is an established consumer financing provider for home improvement projects. It is a nationally licensed sales finance company, and its official website identifies it as an approved FHA Title I lender.
The company is also a subsidiary of Truist Financial Corporation.
These facts provide context about the company, but they do not mean every financing offer is automatically suitable for every homeowner.
A legitimate financing provider can still offer a loan whose cost or repayment conditions are not appropriate for a particular household.
Homeowners should evaluate the specific loan agreement, the contractor, and the project before proceeding.
Check the Contractor Separately
One of the most important considerations is that Service Finance Company provides financing, while the contractor is responsible for the actual home improvement work.
Before hiring a contractor, consider checking:
-
Relevant state or local licensing requirements
-
Insurance coverage
-
Business reputation
-
Written estimates
-
References, where available
-
Project scope and payment arrangements
The Federal Trade Commission provides consumer guidance on avoiding home improvement scams. Its recommendations include getting written estimates, checking contractors, and avoiding pressure to sign agreements immediately.
You can review the FTC's guidance here:
FTC: How to Avoid a Home Improvement Scam
Service Finance Company Reviews: What Should Borrowers Consider?
Homeowners researching Service Finance Company may encounter reviews on platforms such as Trustpilot and the Better Business Bureau.
These reviews can help readers identify reported customer experiences, concerns, and recurring themes.
However, online reviews should not be treated as a complete picture of the company's performance.
Why Customer Reviews Need Context
People who post online reviews may have particularly positive or negative experiences. Their experiences may not represent all borrowers.
A review may also involve different aspects of a customer's relationship with the company, such as:
-
Loan servicing
-
Payment processing
-
Promotional financing
-
Customer service
-
A dispute with a contractor
-
Confusion about loan terms
A complaint about a contractor's workmanship is not necessarily a complaint about the financing provider. Similarly, a concern about payment servicing may not reflect the contractor's performance.
When evaluating reviews, look for specific details and patterns rather than relying on one comment or a single rating.
How to Use Review Platforms
Trustpilot and BBB can be useful starting points for researching reported customer experiences.
Readers should examine the content of reviews, the dates they were posted, and whether the company has responded to complaints.
Ratings and review counts can change over time. They should be checked directly when making a current assessment.
Neither platform should replace reviewing the actual loan agreement or independently evaluating the contractor.
Pros and Cons of Service Finance Company Home Improvement Financing
Service Finance Company financing may be useful for some homeowners, but it also involves considerations that should be reviewed before accepting an offer.
| Potential Advantage | Potential Drawback |
|---|---|
| Financing may be available through a participating home improvement contractor | Options depend on the contractor and borrower |
| May allow homeowners to spread project costs over time | Borrowing can increase the total cost of the project |
| Different financing structures may be available | Promotional terms can be complex |
| Can provide an alternative to paying the entire project cost upfront | The borrower assumes a repayment obligation |
| May support projects such as HVAC, roofing, and remodeling | Financing does not guarantee the quality of the contractor's work |
The most important question is whether the financing arrangement is appropriate for the project and the homeowner's financial circumstances.
Service Finance Company vs. Other Home Improvement Financing Options
Service Finance Company is not the only way to finance a home improvement project.
Homeowners may also consider personal loans, bank or credit union loans, home equity loans, HELOCs, or paying with savings.
Each option has different advantages, risks, and requirements.
Service Finance Company vs. a Personal Loan
A personal loan may be available from a bank, credit union, or online lender.
Personal loans are often unsecured, meaning they do not require the borrower to pledge a home as collateral. However, the available interest rate, loan amount, and repayment term depend on the lender and the borrower's application.
A personal loan may be useful when a homeowner wants to compare financing independently of the contractor's offer.
Service Finance Company vs. a Home Equity Loan
A home equity loan allows a homeowner to borrow against the equity in their property.
These loans may offer different repayment structures and interest rates compared with contractor-arranged financing.
However, home equity loans are generally secured by the property. Failure to repay can put the home at risk.
Homeowners should consider this risk carefully before borrowing against their house.
Service Finance Company vs. a HELOC
A home equity line of credit, or HELOC, provides access to a revolving credit line secured by the home.
Unlike a fixed-amount installment loan, a HELOC allows borrowers to draw funds as needed, subject to the lender's terms.
This flexibility may be useful for projects with multiple stages or changing costs. However, HELOCs can involve variable interest rates and repayment structures that require careful planning.
Service Finance Company vs. Paying With Savings
Using savings avoids taking on a new loan and paying interest.
However, paying for a large project entirely from savings may reduce the funds available for emergencies or other financial goals.
Homeowners should balance the cost of borrowing against the importance of maintaining an adequate financial reserve.
Comparing the Alternatives
| Financing Option | General Structure | Main Consideration |
|---|---|---|
| Service Finance Company | Contractor-arranged installment financing | Review the specific promotional or installment terms |
| Personal loan | Usually a fixed-amount loan from a lender | Compare APR, repayment term, and total cost |
| Home equity loan | Loan secured by home equity | The property is collateral |
| HELOC | Revolving credit line secured by home equity | Rates and repayment structures may vary |
| Savings | Pay the project cost without borrowing | Consider the impact on emergency savings |
No option is automatically best for every homeowner. Comparing the actual terms of available offers is more useful than choosing based only on the name of the financing provider.
What Happens If There Is a Problem With the Contractor?
Home improvement financing can create an important distinction between the loan and the work being performed.
For example, a homeowner may experience a project delay, incomplete installation, or disagreement about workmanship.
The contractor is responsible for the work under the home improvement contract. Service Finance Company is responsible for the financing relationship under the loan agreement.
A dispute with the contractor does not necessarily cancel the loan or automatically stop the borrower's payment obligations.
Keep Documentation
If a problem occurs, homeowners should preserve relevant records, including:
-
The signed home improvement contract
-
The financing agreement
-
The contractor's estimate
-
Invoices and payment records
-
Photographs of the project
-
Emails, messages, and other communications
-
Warranty documents
These records can help explain the nature of the dispute.
Contact the Appropriate Parties
Homeowners may need to communicate with both the contractor and Service Finance Company, depending on the issue.
A workmanship problem should generally be raised with the contractor. A question about loan servicing or payment terms should be directed to the financing provider.
If the dispute involves possible fraud, deceptive practices, or a serious consumer-protection concern, the homeowner may also consider contacting the relevant state consumer protection agency or seeking qualified legal advice.
The appropriate next steps depend on the facts, the agreement, and applicable law.
Conclusion
Service Finance Company provides home improvement financing through participating contractors, allowing eligible homeowners to spread the cost of projects such as HVAC installation, roofing, window replacement, and remodeling over time.
Its financing options may include promotional offers and longer-term installment loans. However, the cost and conditions of each loan depend on the specific agreement.
Before accepting financing, homeowners should compare the APR, monthly payment, repayment term, total repayment cost, promotional conditions, and applicable fees. They should also evaluate the contractor independently and ensure that the home improvement contract clearly describes the work.
Service Finance Company may be a useful financing option for some home improvement projects, but the best decision depends on the homeowner's budget, the contractor's reliability, and the terms of the loan. Reviewing the complete agreement and comparing alternatives can help homeowners make a more informed financial decision.
Frequently asked questions
1. Where can I find the interest-free promotional terms in my Service Finance loan agreement?
Review your loan agreement and promotional disclosures for the offer's duration, payment requirements, and conditions. Confirm whether the offer is truly interest-free or deferred-interest financing. Do not rely only on a contractor's verbal explanation; the written agreement controls the terms.
2. Can I add more home improvement work to an existing Service Finance loan?
Additional work may require a separate loan. Service Finance's FAQ indicates that additional work after the dealer has been paid requires a new loan. Confirm the arrangement with the contractor and Service Finance before authorizing extra work.
3. Can I pay off my Service Finance loan early?
Service Finance's FAQ states that its loans do not have a prepayment penalty. However, review your specific loan agreement and confirm the payoff amount with the company before making an early payment.

Daniel Brooks writes practical content about personal finance, budgeting, saving, credit, banking, taxes, and everyday money decisions. His work focuses on explaining financial topics in straightforward language and help...